Low-Risk Stocks Outperform High-Risk Stocks

. July 10, 2014

Have you heard the saying, "Low risk, low return?" Stocks that go up and down less than the market have low risk (low beta) and should offer lower returns than high-beta stocks. This is the common-sense relationship between risk and return predicted by the capital asset pricing model (CAPM), which most professionals would use to manage your money.

The truth may surprise you.

Real-world data contradict CAPM's predictions. A paper titled Country and Sector Drive Low-Volatility Investing in Global Equity Markets finds that a portfolio of low-risk stocks formed from the cap-weighted MSCI World Index has a return that is higher than that of the index itself.

From 1978 to 1996, the low-risk portfolio had a return of 18.5% (Sharpe ratio 0.98), while the index had a return of only 15.0% (Sharpe ratio 0.56). From 1997 to 2012, the low-risk portfolio had a return of 9.6% (Sharpe ratio 0.74), while the index had a return of only 5.5% (Sharpe ratio 0.17).

It's worth pointing out that it's easy to beat the cap-weighted index, despite what some experts say. Even picking stocks randomly will do it. But one of the few things worse than a cap-weighted index is a portfolio made up of high-risk, high-beta stocks. (See Equal-Weight Benchmarking, p. 3.)

The chart below, taken from the paper, explains why the low-risk strategy works.
Beta and Up/Down Capture by Min Vol Strategy
The low-risk portfolio, represented by the tan bars in the chart, has a beta of 51%, meaning that when the index goes up or down, it should move 51% as much as the index does. "Low risk, low return," right?

But the chart shows that this isn't actually what happens. When the index goes up, the low-risk portfolio goes up more than its beta says it should, as reflected in the upside capture of 64%. The return is 1.25 times what it's "supposed" to be.

When the index goes down, the low-risk portfolio goes down less than its beta says it should, as reflected in the downside capture of 32%. The loss is only 0.63 times as large as it's "supposed" to be.

The low-risk portfolio outperforms the index over a long period of time because it outperforms its beta in both up and down markets.

(The blue bars in the chart shows that the low-risk strategy also works if you group the stocks by country and sector first and then build a portfolio based on the lowest-risk country/sector combinations. The paper describes this in more detail.)

A spate of articles has come out recently saying that low-risk portfolios haven't worked in the past few years, since their return has been lower than the market's return. To evaluate these criticisms, look at the beta of a low-risk portfolio. If its beta is 50%, it is half as risky as the market, and it should only provide half the return (assuming interest rates are near zero). If its return is higher than half of the market's return, the portfolio is doing what it's supposed to.

Low-risk stocks do better than stocks as a whole because their return is only slightly lower in bull markets and is much better than average in bear markets.

Some people use leverage, borrowing money at a low rate, to be able to buy a larger amount of a low-risk portfolio, making its beta equal to that of the index. Since the low-risk portfolio already has a higher long-term return than the index does, leverage increases that return even more.

Common Sense is Not Common True

If you need more evidence, look at the chart below, taken from a paper titled The Volatility Effect: Lower Risk Without Lower Return. The chart has a line moving upward from left to right showing a low return for low-risk (low beta) stocks. The line was drawn using predictions from CAPM.
Theoretical relation between beta and return
There's nothing in the chart that would surprise most financial professionals. The problem is that I cheated.

It's not actually the chart taken from the paper. I erased the real-world data before showing it to you.

Here's the real chart:
Empirical versus theoretical relation between beta and return
The data points don't fit the line at all. In fact, they seem to trend in the opposite direction. Low-risk, low beta portfolios have higher returns than high-risk, high beta portfolios.

A paper titled Betting Against Beta shows that low-risk assets outperform their betas for U.S. stocks, 20 international markets, the Treasury bond market, the corporate bond market, and the futures markets.

The paper hypothesizes that low-risk works because of mutual fund managers. They try to outperform the market, but they're not allowed to use leverage, so they buy high-risk stocks instead. This drives up the price of high-risk stocks, causing a drag on returns, while leaving low-risk stocks underpriced.

The authors of the paper look at actual portfolios to test their hypothesis:

We study the equity portfolios of mutual funds and individual investors, which are likely to be constrained. Consistent with the model, we find that these investors hold portfolios with average betas above 1. On the other side of the market, we find that leveraged buyout (LBO) funds acquire firms with average betas below 1 and apply leverage. Similarly, looking at the holdings of Berkshire Hathaway, we see that Warren Buffett bets against beta by buying low-beta stocks and applying leverage.
Mutual funds hold risky, high-beta stocks. Warren Buffett, on the other hand, buys low-risk, low-beta stocks and applies leverage, accessing money at favorable terms so he can buy more.

People think leverage is risky, but risk depends on what the leverage is buying. The data suggest that using leverage to buy low-risk stocks is a better idea than buying high-risk stocks without leverage. An alternative, sort of like using leverage, is to change a portfolio over to low-risk stocks and to use more of the portfolio than normal for stocks and less for bonds.

Another way to invest in low risk, discussed in a paper titled Capitalizing on the Greatest Anomaly in Finance with Mutual Funds, is to buy funds with low betas.

There are also specially-designed low-risk exchange-traded funds that can be bought and sold like individual stocks. They have favorably low expense ratios. However, retirement accounts typically have limited choices that may not include these funds.

Be Brave

What we've discussed may make financial professionals uncomfortable. The low-risk, high-return phenomenon has been known since the 1970's, but people are still taught the capital asset pricing model in school, and they still use it to manage money.

Strategies with academic research behind them, like low-risk investing, value, and momentum, get ignored in favor of passive investing. Beating the market is said to be hard, despite evidence that a cap-weighted market index like the S&P 500 historically has been beaten by picking stocks randomly.

If you challenge the capital asset pricing model, you challenge what people were taught in school. You challenge what they do for a living. You challenge their worldview.

Think different. Be brave.


Cheap Stocks Outperform Expensive Stocks

. July 2, 2014

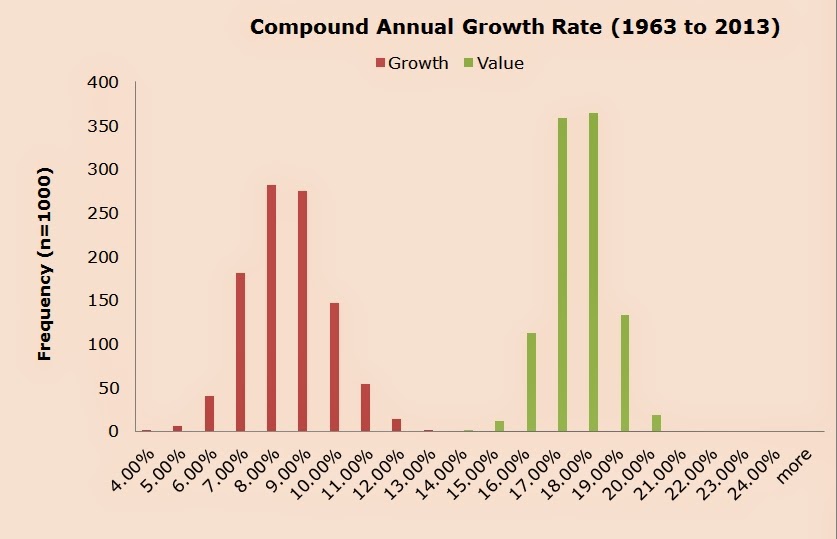
Here's a recent article testing growth ("expensive") stocks and value ("cheap") stocks. The test finds that, very consistently, value has higher returns and lower volatility risk than growth. The U.S. stock market is currently on the expensive side, and stock markets outside the U.S., especially emerging markets, are on the cheap side.

A chart taken from the article:
Growth vs. value: Compound annual growth rate

There is a lot of academic evidence suggesting that value stocks should be offered as a benchmark to follow. The evidence is so strong that most academic studies actually use value as a control.

One of the problems with cap-weighting (for example, the S&P 500 index is cap-weighted) is that cap-weighting gives more weight to stocks that have gone up in price and gotten more expensive. This is probably the reason that cap-weighting underperforms almost every other method of indexing - even an indexing method that picks stocks randomly.

Click through to read the entire article: Never Buy Expensive Stocks. Period.

One can't even simulate a scenario where a diversified portfolio of 30 expensive stocks can beat the worst performing portfolio of 30 cheap stocks. Why investors allocate to expensive, or "growth," stocks is beyond me.

Picking Stocks Randomly Beats the Market

. July 1, 2014

Is it a good thing to put your money "in the market?" That depends on what you mean. Most people will steer you toward cap-weighted funds (the S&P 500, for example, is a cap-weighted index). Research suggests that of all the ways to balance stocks in a portfolio, cap-weighting is one of the worst.

Article in plain English: Index Monkeys Beat Cap-Weighting 

Researchers have found that equity indices constructed randomly by 'monkeys' would produce higher risk-adjusted returns than an equivalent market capitalisation-weighted index over the last 40 years.

White paper: Equal-Weighted Benchmarking: Raising the Monkey Bars 
Given the disappointing performance of active managers, it is particularly surprising how many alternatively weighted indices outperformed the cap-weighted S&P 500.... A more comprehensive critique conducted by the Cass Business School showed that “...equity indices constructed randomly by 'monkeys' would have produced higher risk-adjusted returns than an equivalent market capitalization-weighted index over the last 40 years. A study based on monthly U.S. share data from 1968 to 2011 found nearly all 10 million indices weighted by chance delivered vastly superior returns.” This counterintuitive and remarkable result deserves specific emphasis. According to these results, in the period from 1969 to 2011, if you had picked stocks at random, there is a 99.9% chance you would have beaten the market.

Facebook Page on Quantitative Trading

. June 26, 2014

Over the past few years, I've gravitated toward multi-strategy thinking. What strategies tend to do well when momentum underperforms for a few years? What strategies have a low correlation with momentum that can help diversify it?

The strategies have been debated in academic papers for decades, so they're not hard to find. Integrating them into a portfolio is more of a challenge.

The obvious way to combine strategies is to use leverage: for example, to reduce the market risk of a momentum strategy as much as possible, to do the same thing with a value strategy, and then to borrow money at a low rate in order to get exposure to both. There is a risk that momentum and value will both underperform at the same time and that the leverage will end up hurting the portfolio. Now imagine managing the risk of four or eight strategies integrated in the same way.

I've chosen not to go with the obvious method, but instead to pick from a universe of exchange-traded funds using a quantitative method to select funds based on multiple strategies. The tradeoff is the increased amount of information I have to process to actually put on a trade. Most people would say that this is more trouble than it's worth.

So far, I've hesitated to post about anything other than trend-following momentum using moving averages other than on the resources page. Most people aren't obsessed with trading, and information overload might cause them to give up on it completely.

That's why I've been posting the information overload links to a Facebook page for the past three years. If you really are obsessed, check it out:

Play the Lotto Like a Trader

. April 2, 2012

Good odds look better than they actually are. A $540 million jackpot isn't worth $540 million if they pay it out over decades, once you take inflation and unearned interest into account. Calculate the odds based on today's lump sum payout. It will always be less than the advertised jackpot.

Photo by Mike Fleming
And then there are taxes. You'll lose nearly half of the lump sum payout to the government unless you can find a way to defer or eliminate being taxed on your winnings.

And then there's the law of diminishing returns. Dollar for dollar, $1000 spent on lottery tickets is a house payment that will keep some people from foreclosure. $1000 after you already have $100,000 cash is less precious. An extra $1000 after you have $540 million is peanuts.

Would you buy $1000 in lottery tickets to have an 11% chance to win $10,000? How about $1 million in lottery tickets to have an 11% chance to win $10 million?

Some of us would go for the first option, though I honestly don't see why after taxes and deferred payments are taken into account. Almost no one would go for the second: $1 million in your pocket today is not worth risking to have $10 million, which will not really be worth ten times as much to you.

When it comes to money, slow and steady wins the race.

More here: Is the $540 Million Lottery a Good Bet?

A Free Education

. December 5, 2011

Reading as a form of self-education becomes more important the older a person gets. After college, reading becomes the primary form of self-education.

One of the best ways for a job applicant to elevate himself to the #1 position is to maintain a blog with book reviews and articles on topics related to the field the person wants to work in.

Getting good grades in college shows that the applicant has read in his field, but maintaining the blog shows that it is likely that he will continue to read widely and educate himself. It's an education with no tuition for the employee and no cost to the employer: a win for both.

Since one of the keys to self-funding is to earn more and spend less, preferably in a career where you can find fulfillment through service, it makes sense to make the most of your opportunities when applying for jobs.

Great Reads: A Flood of Trading Links

. November 15, 2011

Don't say I didn't warn you.

Trading and Investing

The Ivy Portfolio vs. Ivy League endowments last year. (Mebane Faber)
Trend-following indicators reduce downside volatility. (MarketSci)
When momentum is poor, sell out. (Research Puzzle) 
Ideas about volatility-adjusted relative strength. (CXO Advisory)
Individual stocks mean-revert from month to month; industries trend. (SSRN)
Anomalies like momentum and value to go in and out of style. (CXO Advisory)
Selling puts or calls according to trend. (CXO Advisory)
Managed futures can save your tail. (Steven Koomar)
Investors allocate to the wrong asset class at the wrong time. (Mebane Faber)

A Softer World: 703
Software and brokers for options trading. (Condor Options)
Yes, bonds can be volatile instruments. Surprised? (ETF Replay)
Investing lessons from a pianist. (Marc Faber)
How to explain short selling to your mother. (BC Lund)
Are you a deranged trader? (Surly Trader)

In complex transactions involving a lot of people, be cynical. (Aleph)
"Never, ever take counterparty risk." (Reformed Broker)

It may be cheaper to buy ETF's than mutual funds. (Mebane Faber)
"Funds of funds face a huge hurdle because of the high fees." (Mebane Faber)
Can active managers add value when everything is correlated? (ETF Replay)
Commodity indices behave like mostly energy. (MarketSci)
Asset classes are becoming more correlated. (MarketSci)

Some of hedge funds' returns come from liquidity risk. (CXO Advisory)
Be careful about shorting that VXX. (MarketSci)
The state of short-term mean reversion. (MarketSci)
What happens to P/E ratios when rates and inflation change? (Mebane Faber)

Average market performance on the last day of the quarter. (MarketSci)
Average market performance on the first day of the quarter. (MarketSci)
The stock market tends to be strong in the fourth quarter. (MarketSci)
Dividend payers: less volatility and a significantly higher return. (SurlyTrader) 

Affordable Living

If you were a millionaire, would you act like one? (Reformed Broker)

An emergency fund can indirectly provide a good return on the money. (Aleph)
How to extend the life of laptop batteries. (Education Tech News)
Affordable ways to create gifts for men. (She So Crafty)

Career

Blogging is like working out. (The Basis Point)
How to find a job in finance. (Aleph)

Man Links

The importance of trusting men in your circle. (The Art of Manliness)
Are you a spectator or a doer? (The Art of Manliness)
Leaders lead people through fear. (Donald Miller)

Stop living for the approval of women. People-pleaser. (Art of Manliness)
Don't live for your mother's approval, either. (Art of Manliness)
Men, stick to your guns. (Art of Manliness)

How to improve your posture. (Art of Manliness)
The power of morning and evening routines. (Art of Manliness)
How to be the perfect party guest. (Art of Manliness)
Ten cheap date ideas she'll actually love. (Art of Manliness)

Marriage and Family

The personality types that make the best matches. (Personality Page)

Society and Worldview

Churches, are you sure you want your young adults back? (Immerse Journal)

Hypothesis: the efficient market hypothesis led to the financial crisis. (Aleph)

It costs 2% to 5% of GDP to file taxes. Not pay, just to file. (Dan Dascalescu)
Washington, D.C. is booming. What recession? (Reformed Broker)

The Facebook Gross National Happiness indicator. (Facebook)
Welcome to the genomic revolution. (YouTube)

Christian Living

How to stop worrying. (Max Lucado: part 1 and part 2)
"God understood Elijah's weary despair, and he let him sleep." (CCEL)

Technology

Get rid of line breaks that bother you when you copy from the Web. (Text Fixer)

LOL

Why go to college? (SurlyTrader)
Watch out! (Signs of Danger)

Scary church signs. (Ed Stetzer)
How different Christian denominations see each other. (Ed Stetzer)

How to win at Monopoly: buy the orange properties. (BBC)

Penguins attack:

Life is the Adventure

.

I volunteer for Habitat for Humanity on the weekends. I may not enjoy painting my own house, but I like doing it for others.

What words would you use to describe a short-term mission trip? Perhaps not fun, but worthwhile? Difficult? Significant? Memorable? Exciting?

Adventure

The word adventure sums it up for me. We team up and face challenges, overcome them, and come out the other side having achieved a memorable goal. We rescue people. Maybe someone even gets the girl.

Why do we compartmentalize life? Painting is a chore, but Habitat for Humanity is fun. Preparing a lesson is boring, but a short-term mission trip is a thrill. Playing with the kids is tiresome, but soccer is real football.

It's tempting to grind through life waiting for the next great thing. Besides being tedious, the problem with this is that life today may be a preparation for that great thing, but you're not enjoying it.

Some of us may even find that life itself is that great thing, that it was right in front of us all along, and that we can change the world right where we are.

Whistle While You Wait

Time produces compound growth, both for money and for wisdom. If you save money and wait long enough, you'll eventually be able to fund a great adventure.

In the meantime, think about what makes adventures fun. What can you do to make painting the living room more like Habitat for Humanity? Maybe you can bring in a big group, serve them lunch, and let them debate philosophy while splashing paint on each other.

How can playing with your kids become more like a soccer game for you, not just for them?

What if life is the adventure?

Book: Mr. China

. November 10, 2011

Those of us who thirst for adventure get more than we bargain for. Such was the case for Tim Clissold, who moved to China in 1990 in the wake of Tiananmen Square, learned Mandarin, and raised more than $100 million of Wall Street's money with the intent to profitably transform Chinese businesses.

He discovered that the Chinese weren't numbers on a spreadsheet. They were real people, full of guile and greed. Successful business in China meant breaking contracts, speaking in half-truths, secretly moving money around, and staying one step ahead of a controlling but disorganized Communist government.

Chinese businessmen took Wall Street's money and then drove their factories into the ground, moving the capital to other bank accounts so they could start their new, competing factories. They had learned to live by their wits in a Communist world. Why treat these American foreigners any differently?

In the end, Clissold got taken, but so did all the American efforts to invest in China. The fund he helped manage lost money, but it was the only China fund to survive the 1990's intact. Meanwhile, local Chinese companies went public, China's stock market soared, and the standard of living rose rapidly in the coastal cities.

What Can We Learn From This?

As an investor, stick to what you understand. Clissold had a thesis that China was on the verge of a capitalist transformation. He was right, but he lost money. Buying private businesses in a foreign country and trying to improve the management is a venture fraught with difficulties, since there are so many variables to control and even more that we can't see.

If you have an investment thesis but not extensive expertise, it can make more sense to express that thesis by trading liquid markets (stocks, funds, and futures) than to start a business. Managing a business also concentrates your risk. Unless you have a high net worth, it ends up concentrating all your risk in one place, and you can't get out easily if you decide it's not working out.

I used to romanticize the idea of going overseas, as I'm sure many others do. After years of working in China, Clissold's fund lost money, but he learned to appreciate the Chinese as a people rather than just an investment. If this is the main lesson you learn while overseas, will you be satisfied with your life? Yes is a good answer but not an easy one.

I'll leave you with an excerpt from the inside flap:

The idea of China has always exerted a pull on the adventurous type. There is a kind of entrepreneurial Westerner who just can't resist it: red flags, a billion bicycles, and the largest untapped market on earth. What more could they want? After the first few visits, they start to feel more in tune and experience the first stirrings of a fatal ambition: the secret hope of becoming the Mr. China of their time.

In the 1990s, China went through a miraculous transformation from a closed backwater to the workshop of the world. Many smart young men saw this transformation coming and mistook it for their destiny. Not a few rushed East to gain strategic footholds, plant their flags, and prosper. After all, the Chinese had numbers on their side: a seemingly endless population, a thirst for resources, and the tide of history. What they needed was Western knowledge and lots of capital. Or so it seemed...

Mr. China tells the rollicking story of one man's encounter with the Chinese. Armed with hundreds of millions of dollars and a strong sense that he and his partners were -- like missionaries of capitalism -- descending into the industrial past to bring the Chinese into the modern world, Clissold got the education of a lifetime.

The ordinary Chinese workers, business owners, local bureaucrats, and party cadres Clissold encountered were some of the most committed, resourceful, and creative operators he would ever meet. They were happy to take the foreigner's money but resisted just about anything else. At every turn, the locals seemed one step ahead of Clissold's crew threatening to take the Westerners for all they were worth.

In the end, Mr. China isn't a tale of business or an expatriate's love for his adopted land. It's one man's coming-of-age story where he learns to respect and admire the nation he sought to conquer.

Book Review: How Women Help Men Find God

. October 23, 2011

Jesus wasn't a nice guy. And neither should you be.

Few of us have heard the above sentiment expressed in church, let alone explored. Yet, after reading the gospels, it's hard to come away with the impression that Jesus was a safe, predictable person who would have made a good churchgoer.

Can you imagine one of your church's deacons grabbing a flesh-eating whip and creating instant pandemonium in God's house of worship, driving out money changers and overturning their tables?

What Would Jesus Do?

Here's a selection of Jesus' "nice guy" stories from Mark 11 alone: 

He curses a fig tree and says, “May no one ever eat fruit from you again.” Peter notices later that the fig tree has withered.

After driving the money changers from the temple, he says “Is it not written: ‘My house will be called a house of prayer for all nations’? But you have made it ‘a den of robbers.’ ” This definitely isn't perceived as a nice saying, as it prompts the religious authorities to fear Jesus and begin looking for a way to kill Him.

Instead of answering a question, Jesus shoots back more questions. When His questioners fail to answer, Jesus ends the conversation on His own terms (vv. 27-33).


What Have We Done?

According to David Murrow's book How Women Help Men Find God, we've spent the past half century making church a safe, predictable place where families can gather and children can be protected from a cruel world. The unintended consequence is that men now perceive church as a place where women can be safe and successful, and they've shifted their lives to center around things that are culturally perceived as manly, such as work, hobbies, and sporting events.

Murrow thinks that women can help bring men back by being gentle witnesses and by making sacrifices to make church more appealing to men. We can change the decor, create volunteer opportunities men can feel fulfilled in, make our churches more theologically oriented (and make arguing about theology okay), and intentionally encourage discipleship between men.

While all this is important, it dances around something more central, which is the what that is passed down by good theology and man-to-man discipleship. That something is what it means to live the Christian life as a man.

The Art of Manliness

I've written about this before: for example, check out How to Trade Like Zorro. When I step back, though, I think we are rushing to catch up with what those outside of the church have realized for a while now. We no longer live in a culture that understands what it means to be a gentleman, an honorable guy who defends others but has the strength to stand up for the interests of his own family.

We're happy to tell our sons to be nice like Jesus was (whatever that means). Then they get married and feel they have to bend over for that life insurance salesman who pushes the most expensive policies so he can get a big commission up front. We teach our men to be nice, but they're suddenly supposed to summon supernatural courage to share their faith at work or do the right thing at a great cost.

Dave Murrow's books are a great start, but they're also a late start, as the case usually is when the church tries to address a contemporary problem. Non-Christian sites like the Art of Manliness provide a wealth of insight about being men in this relativistic culture. The effort we put into taking every thought captive to the obedience of Christ will be worth it.

If you're really brave, take a look at this parody of our Christian-ized view of masculinity:


Mad Markets

Growing in masculine maturity has a side benefit: It will make you a more effective trader and investor. Markets are driven by fear, greed, and crowd behavior. This creates profit opportunities for us, but only if we're willing to go against the crowd at turning points in the market.

In the moments when we're most tempted to buy or sell, it takes a lot of internal strength to do the opposite. If you're a people-pleaser, you'll always face the strong temptation to do what others tell you to do, even if your trading systems tell you otherwise. Markets are rough on nice guys: just ask Sir Isaac Newton.

Like Zorro, you can follow the crowd when it suits you and buck the trend at the right time. The less other people are able to manipulate your beliefs, the more control you'll have over how you respond to the markets.

I'll leave you with an excerpt from the back cover of How Women Help Men Find God:
Millions of married women worship alone every Sunday. Mothers grieve as their teenage sons abandon the faith. Single women search in vain for godly men.

In this dynamic follow-up to his best-selling Why Men Hate Going to Church, David Murrow speaks directly to women to help them understand the real reasons men resist Christianity. It's the first book of its kind - written to help women reach all the men in their lives - not just their husbands. With straight talk, personal stories, and a dose of good humor, David shows women how to draw men to Christ - without guilt, manipulation, or pushy evangelism.

Volatility Does Matter

. October 1, 2011

On the whole "volatility doesn't matter" thing: Yes, it does.

Imagine if you had a guarantee that your stocks or silver or whatever would be worth in ten years at least what they are worth today. They can't go down.

This Is Indexed: Learning Curves
on Winding Roads
You'd probably feel more comfortable increasing your risk somewhere else. You might start a business, buy a rental property, or take a vacation.

Lower market risk makes you feel more comfortable about taking risk in other areas, and rightly so. People even pay for this privilege: it's called a put option, a form of financial insurance.

If you had a strategy that could keep you out of high-volatility periods of the market, would you use it?

That's what trend-following, a form of momentum trading, does. The market tends to have high volatility when it's going down. Momentum strategies avoid being in the market during those times.

What Happens After the Market Goes Down?

. September 23, 2011

When the stock market has upward momentum, it tends to keep going up. However, downward momentum, like we've had since August, tends to be followed by sideways movement with high volatility, as this post from the MarketSci blog shows. 

It's better to be in Treasury bills than in the market when there's negative momentum. This is both for the lower volatility and to earn interest.

For small investors, this could mean moving to a money market fund until the stock market starts going up again. 

To learn more about momentum, start here.

Great Reads: Should You Buy When the Market's Up or When It's Down?

. September 18, 2011

Trading and Investing

Should you buy when the market's up or when it's down? (CXO Advisory)
A two-year mean reversion effect. (CXO Advisory)
More on mean reversion. (Mebane Faber)

Option selling doubles volatility-adjusted returns. (Mebane Faber)

Do financial firms sell to your rationality or your psychology? (CXO Advisory)

Strategies that short battle the rest of the financial universe. (Slope of Hope)

Old methods of diversification are becoming less effective. (Reformed Broker)
On performance chasing. (Reformed Broker)
The market is becoming more volatile. (Reformed Broker)

The Greek one-year yield was triple digits last week. (Zero Hedge)

Free finance and commodity widgets to put on your Web site. (Oil Price)

Career

On effective promotional marketing. (Internet Marketing Fire)

Twenty-five quotes from Margaret Thatcher. (ListVerse)

"The best writing advice I've ever received." (Donald Miller)

Affordable Living

"How can I afford to stay home with my baby?" (Baby Center)

How to shop for your own health care. (CNBC)

The student loan bubble, illustrated. (Reformed Broker)

Edmond, OK tops CNBC's "Best Suburbs" list. (Edmond Sun)

Walking with God

Dealing with the death of a parent. (Fabs Harford)
Tired of being 'gospel-ed'. (Fabs Harford)

LOL

A postman's revenge. (YouTube)

Abstruse Goose: Get it?

Book Review: The Total Money Makeover

. September 17, 2011

In this book, Dave Ramsey lays out a brilliant plan for getting out of debt.  It's brilliant because any rational human being would see it as sub-optimal, but Ramsey realizes something important about human nature. We're not rational.

A rational plan for paying down debt would be to tackle the highest-interest debt first, keeping only what you need for one month in a savings account. An emergency fund would make little sense, as you could borrow from credit cards for that purpose.

Ramsey, on the other hand, realizes that most of us don't have the discipline to follow that plan. If we did, we wouldn't be heavily indebted in the first place. A cash emergency fund meets our psychological desire for security. Paying down the smallest loan first, regardless of interest rate, gives us the chemical rush that comes from successfully getting rid of the first loan payment.

Total commitment to the plan is necessary to override our cultural desire to keep up with the Joneses. The Joneses borrow to maintain their lifestyle. Getting rid of debt requires that we do the opposite. The key phrase in the book is, "If you will learn to live like no one else [frugally], later you can live like no one else [wealthily]."

Beef

My one quibble with the book, and it's a major one, is his investing methodology. Ramsey claims that you can make a 12% annual return by buying and holding mutual funds with the best long-term track records. He recommends this asset allocation (p. 157, 2007 edition):

25% Large cap stocks
25% Mid cap stocks
25% International stocks
25% Small cap/emerging market stocks
It's not the 12% that I disagree with. There are simple trading methodologies, such as momentum, that achieve compound annual returns in that neighborhood with low volatility. A market with a high return (momentum) over the past 12 months tends to produce a high return in the following 12 months.

The kicker is that the momentum effect disappears if you look back more than a year. Markets that had strong returns two years ago tend to underperform going forward. This is called mean reversion.

What if a large-cap manager got his track record by investing in a sector that happened to outperform large-cap stocks in general? If that sector mean-reverts, his outperformance will turn into underperformance. Think about home prices, which moved steadily upward from World War II until 2005. Those who bought real estate based on that track record suffered large losses from 2006 to 2009.

If a fund manager uses trading strategies, mean reversion might not apply. Strategies like value (buying "cheap") and momentum (following trends) don't disappear permanently the way the railroad, utility, and communications booms did. But these strategies aren't part of Ramsey's asset allocation.

A long-term track record is only an asset if you have a good reason to think that the manager's outperformance will continue.

Recommended, with Caveats

If you're in debt right now, Ramsey's approach is psychologically tailored to get you financially free. I recommend the book for that purpose. Borrow it for free at the public library.

Once you're out of debt, you can use the income that used to go to debt payments toward self-funding a ministry dream. For this, Mebane Faber's book on momentum investing, The Ivy Portfolio, is a good read. I've also written a post on how momentum works. 

I'll leave you with some excerpts from Dave Ramsey's book The Total Money Makeover:

Having been a millionaire and gone broke, I dug my way out by making a decision about looking good versus being good. Looking good is when your broke friends are impressed by what you drive, and being good is having more money than they have.

Are you starting to realize that The Total Money makeover is also in your heart? You have to reach the point that what people think is not your primary motivator. Reaching the goal is the motivator. Do you remember the circus game where you swing the large hammer over your head to hit the hit the lever to send a weight up to a pole to ring the bell? You reach the point that you want to ring the bell! Who cares if you are a ninety-eight pound weaking with gawky form? The girls are still impressed when the bell is rung. When the goal, not how you look, begins to matter, you are on your way to a Total Money Makeover. (p. 33, 2007 edition)
 Here's a quote from the inside jacket:
Instead of promising the normal dose of quick fixes, Ramsey offers a bold, no-nonsense approach to money matters, providing not only the how-to but also a grounded and uplifting hope for getting out of debt and achieving total financial health.

Ramsey debunks the many myths of money (exposing the dangers of cash advance, rent-to-own, debt consolidation) and attacks the illusions and downright deceptions of the American dream, which encourages nothing but overspending and massive amounts of debt. "Don't even consider keeping up with the Joneses," Ramsey declares in his typically candid style. "They're broke!"

He gives sure-fire ways to build up savings for emergency funds, for your kids' college, and for your retirement, and he supplements this wisdom with heartfelt stories from real people just like you - people who were once languishing in debt but are now flexing their strong fiscal physique.

The Total Money Makeover is all about "renewing your mind," using God's ways of handling money (over 800 scriptures deal with money) to be "transformed" (made over). It's a plan to stop being "conformed" to the ways of the world and as ridiculously broke as the rest of our culture.

And this isn't theory. It works every single time. It works because it is simple. It works because it gets to the heart of the money problems: you.

Book Review: How to Retire Overseas

.

How to Retire Overseas is the best book I've seen on making a permanent move to outside the United States. It lists fourteen countries where it's possible to have a comfortable, safe middle-class life for less money than in the U.S.

The book rates each country on cost of living, cost of housing, climate, health care, infrastructure, accessibility to the U.S., language, culture/recreation/entertainment, taxes, special benefits for foreign retirees, and education/schools.

The author, who has lived and raised children abroad for twenty-five years, gives specific advice for people in various life situations. She provides details about buying health insurance, which areas are suitable for raising and schooling children, and three countries where it's possible to retire without paying local taxes.

My favorite chapters are the ones about settling in and overcoming challenges and cultural differences. Despite its high cost of living, the United States is still best place for Americans to fit in and get work done. Overseas, it can be a hassle to do simple things like open a bank account, navigate city streets, and make utility payments. Most places don't have the combination of work ethic, infrastructure, and freedom to do business that we have. Despite this book's title and aim, I've become more convinced that there's no place like home.

If you've always wanted to be a missionary but haven't been able to raise the funding, one possible path is to self-fund. For this purpose, I highly recommend reading How to Retire Overseas.

I'll leave you with an excerpt from the inside jacket:

Imagine yourself at home- on the front steps leading to a sandy white Caribbean beach, sitting atop a balcony overlooking the streets in a bustling Latin American city, or inside a hillside villa in Europe- the retirement of your dreams. With a dash of adventure and an ounce of planning, you can turn your fantasies into reality- on any budget, without increasing your bills or sacrificing your lifestyle.

In this definitive guide, author Kathleen Peddicord uses over twenty-five years of experience to show anyone how to retire overseas, with or without retirement income. By providing critical questions for readers to answer, Peddicord helps determine where your ideal overseas home is located. Once you know where you're headed, she outlines how to handle the move itself, and guides you through the process of establishing yourself in a foreign country, including how to:

*Find and rent or own a home
*Research and understand your tax liability
*Establish secure bank accounts
*Obtain health insurance and medical care
*Make friends in your new home
*Avoid common pitfalls and mistakes

With advice from the author's own experience living abroad as well as personal stories from the hundreds of retirees she's helped achieve their retirement goals, this essential guide helps anyone plan for and enjoy a new life overseas- for less money than a traditional retirement in the United States.

How to Trade Like Zorro

. September 11, 2011

Have you heard this song? "Billy, don't be a hero; don't be a fool with your life."

Tom Sosnoff quotes this song to describe traders who put on too much risk and lose everything when the market goes the wrong way. But is there a Christian heroism that involves taking smart risks?

Simmering ideas about heroism came together for me yesterday while I was watching The Mask of Zorro.

Let me list some of the myths about heroism first:

  • "Heroes take control of their environments."
  • "They bend others to their will."
  • "They never run from a fight."
  • "They take insane risks and glory in it."
Keep these myths in mind as you watch this fight scene from the movie:


Do you see the contrast between Zorro and the myths described above?
  • Zorro doesn't brutally take control of his environment. He doesn't force others to obey. Instead, he sets up situations where people play into his hands. He anticipates what they're going to do and makes plans that seem risky but actually have a high probability of success. "[Captain Love] will come into your circle soon enough. You need not chase him."

  • Zorro is not afraid to run from a fight. He always engages others on his own terms. Sometimes this means running, sometimes it means letting others attack, and sometimes it involves laying traps. He hides in the shadows and shows himself when he's ready. He breaks his attackers apart into small groups and tackles those groups one at a time.

  • Zorro takes smart, well-planned risks. His goal in this particular battle is to strike fear in the hearts of his enemies. He takes the necessary risks necessary without going overboard. He escapes while he's ahead.
Live to Fight Another Day

As a one-man show, Zorro absolutely cannot afford to get crippled. Everything depends on his staying alive. This is a lot like trading. If you depend on trading as an insurance policy or the means to fund a ministry dream, you can't afford large losses.

My own trading strategy allows for a lot of unexpected problems. I know that eventually I'll be wrong, face bear markets, deal with high volatility, and encounter market crashes. I get to pick and choose the right trades for each set of market conditions. I can't control the market, but I can choose trades on my own terms.

There's also a time to run away in trading. When the favorable conditions for a trade go away, I close the trade out, sometimes at a loss. This is preferable to taking the risk of larger losses with no statistical profit advantage to justify that risk. The most important thing is to live to fight again tomorrow.

Don't Be a Hero

People tell me all the time that trading is too risky. But I see those same people spending all of their liquid capital putting 20% down or less on a house. That, to me, is risky: if the house goes down in value or the owners can't make their payments, the owners lose all of their money. They may even end up in foreclosure and then bankruptcy. How will they support their children then?

When the movie ends, there's only one Zorro. If he dies, there won't be a sequel. No one will get the girl. Would Zorro take the kinds of risks that most homeowners do?

Zorro as a Type of Christ

If the idea of Zorro as a trader isn't bizarre enough, imagine Zorro as a representation of Christ.
  • Jesus had the power to take control of His environment, but He took on flesh and came into a sin-corrupted world as a helpless baby.

  • He didn't force others to obey but made His points through intelligent arguments and Scripture. Depraved human beings hated Him for it.

  • Jesus engaged others on His own terms. He answered questions with more questions or complete silence. He told parables instead of explaining things directly. After a while, no one dared to ask Him any more questions.

  • Jesus didn't feel obligated to fight. He slipped away from crowds and sometimes refused to do what people requested. He knew when people were trying to trap Him and only allowed it to happen on His own terms: at the cross.
A better understanding of Christian heroism and the nature of Christ will make us better traders. There's a lot at stake. Dream big, take smart risks - and get the girl.

Great Reads: Sir Isaac Newton as a trend-follower?

.

Trading and Investing

What if Sir Isaac Newton had been a trend-follower? (Mebane Faber)
Missing the "ten best days" isn't such a bad thing. (Mebane Faber)

September is a weak month for the stock market. (Surly Trader)
Positive feedback loops and market crashes. (Surly Trader)

What happens to bond prices as interest rates change? (Mebane Faber)

Stock market valuation models: P/E ratios. (Mebane Faber)
"Cheap" is not always cheap. Huh? (Reformed Broker)

Recession odds at 50%? (Reformed Broker)

Which countries will dominate the global economy in 2030? (Economist)
Economic indicators color-coded on a world map. (TradingEconomics)

What are options good for? (Condor Options)
The spread between volatility indices has interesting information. (Option Pit)

How good is published academic research? (Marginal Revolution)

Career

Who lost work during the Great Recession? (New York Times)

How do you successfully market to your best customers? (Seth Godin)
Expensive advice isn't necessarily better. (Seth Godin)
Is your work environment still organized using a factory model? (Seth Godin)

Comparison of video hosting services. (Wikipedia)

Watch out for conflicts of interest. (Dilbert)
Watch not just what you say, but how you say it. (Dilbert)
On making decisions without thinking. (Dilbert)
Did you mean that? (Dilbert)
Creativity? (Dibert)

Theology

Cornelius Van Til: downloadable audio and courses. (Gospel Coalition)

Marriage and Family

One hundred must-see movies for men. (Art of Manliness)

What would happen if you let your defenses down? (Boundless Line)

LOL

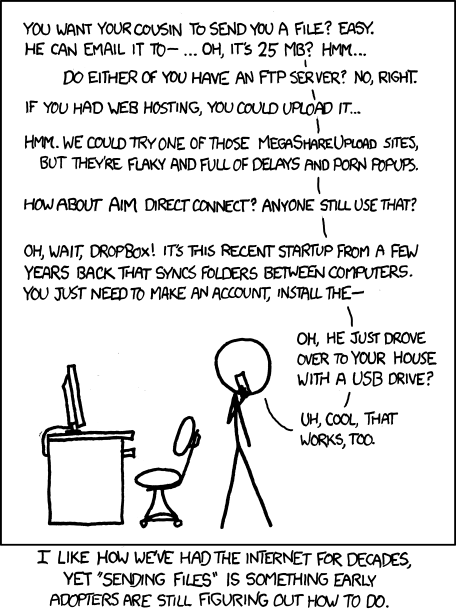
We're still figuring out how to send files to people. (xkcd)

xkcd: Are interest rates low enough for you yet?

Life as Mission

.

In America, leisure is treated almost as if it's a human right. We grow up in a youth subculture which feeds and celebrates distinctly childish interests. Remember this "Toys 'R Us" commercial from the 1980's?


Then we have eight-hour work days, mandatory breaks, weekends and some three-day weekends, vacation, and even a retirement that's supposed to be funded by the government.

The printing press,
an early robo-slave
This is the result of increased productivity. Each generation has an increasingly efficient set of robo-slaves that does our laundry, waters our lawns, and even deposits our paychecks for us. There are robo-slaves at work that make copies, ding our co-workers' phones with text messages, and do complex analytical work. As computers become more capable, we don't have to work as hard.
With all this leisure time, why aren't we happier?

Part of the reason is that we are built for mission. God gave Adam work to do. Unproductive leisure is not the kind of joy-filled work Adam did before the Fall.

I suggest three ways to bring mission back into the work you do.
  1. Redeem the work you're already doing. What can you do to love God and love your neighbor in the responsibilities you've already been given? Can you be an agent of change in your workplace's culture?

  2. Replace some leisure time with short-term mission. You don't have to go overseas to do this. If you're going to take a three-day weekend anyway, is there something your family can do that would be both enjoyable and Gospel-centered? Helping others might bring your family more happiness and fulfillment than a weekend lounging around playing video games.

  3. Cultivate long-term mission-oriented goals. Again, this can integrate into your existing plans. Are you saving for retirement anyway? Can some of those funds be used to make your retirement a period of service and not just leisure? Are you saving and investing enough to have a reasonable chance of getting there?
I'll leave you with a few quotes from Fabs Harford's read-worthy blog post, Why Am I Weary?
Maybe the reason we’re weary is not because we’re pouring our lives out for others, but because we aren’t.

Life can feel like a chore if we aren’t on mission....

Want to be refreshed?  Want to be like a watered garden?  Want to be satisfied and guided continually?  Care about people.  Pour yourself out for them...

What if God ordained mission for us; to provide energy and joy; and what if satan has kept us from that great stream of grace by convincing us that mission is a threat to our energy and joy?

Or, maybe there’s another way Satan could sabotage the design of mission.  There are no shortage of us who are pouring ourselves out without the promised result in Isaiah because when we do engage in mission, we act as if we’re doing God a favor.

Life feels like a chore because we serve out of duty and not delight.
 Read her full post here.

On Being Wrong

.

Admitting we're wrong takes character. It means denying our own supposed omniscience and sovereignty. We live in a world which is uncertain and seems to make a habit of pointing out our mistakes.

Trading is one of those areas where our unwillingness to be wrong costs money. Do you remember when the S&P downgraded the U.S. credit rating in August? Nearly everyone I knew, including I, was saying that this downgrade would inevitably lead to higher long-term interest rates and that it was a great time to short bonds. As it turns out, the opposite happened. Long-term interest rates are lower today than they were in August.

We're Limited

Because we're human beings and not God, we have only a limited ability to take in and process information. As a result, we tend to think that whatever information we have is a comprehensive picture of the world, when in fact other things we haven't considered may be more important.

Why did interest rates go down in August? In retrospect, maybe the Euro zone crisis or the possibility of a recession in the emerging markets caused capital to flee to U.S. Treasuries, causing interest rates to fall despite the credit downgrade. It takes character to admit that we don't really know.

Follow Momentum

Using momentum as a market timing tool helps us admit when we're wrong. We buy in when upward momentum appears and sell when that momentum goes away. We admit that whatever our opinions about the world are, the potential cost of being wrong is far higher than the potential cost of selling too early. People who bought stocks in 2001 and early 2008 because the market was "cheap" and "couldn't go down any further" paid the price in a big way.

Because admitting that we're wrong requires humility, following a trading plan based on momentum takes character. We have to be willing to let mathematically calculated trading signals override our own opinions.

For more about momentum trading, start here.

Take a look at the TED talk below for more about the importance of understanding our fallibility.

Most of us will do anything to avoid being wrong. But what if we're wrong about that? "Wrongologist" Kathryn Schulz makes a compelling case for not just admitting but embracing our fallibility.

Great Reads: People Listen to Stories, Not Facts

. September 4, 2011

Career

People listen to stories, not facts. (Seth Godin)
Two earthquake-related thoughts about crowd behavior. (Seth Godin)
You can either seek to get more out of an opportunity or less. (Seth Godin)

Will tomorrow's business stars come from agriculture? (Reformed Broker)

Keep shortcuts to commonly used Web pages on your desktop. (Ask Leo)

If you could have any super-power, what would it be? (Reformed Broker)

How to handle excellent and/or devastating news. (This Is Indexed)

In the information age, information is no longer precious. (Seth Godin)
Is the Internet empowering or censoring citizens? (YouTube)


Trading and Investing

All strategies, including buy and hold, involve forecasting. (Strom Macro)
Teachers of "buy and hold" may have a conflict of interest. (Reformed Broker)

An interesting take on momentum investing metrics. (Vector Grader)

Hedge funds have delivered positive alpha since 1995. (Institutional Investor)

Marriage and Family

Divorce rates: things can be more complicated than they seem. (Boundless Line)

LOL

Which way is the market going? (Abstruse Goose)

Depth perception. (xkcd)
"I'm sorry." (xkcd)

Things that make your skin crawl. (This Is Indexed)

Logic. (Dilbert)

YouTube

Schools kill creativity.